Savings You Need Before Quitting Your Job
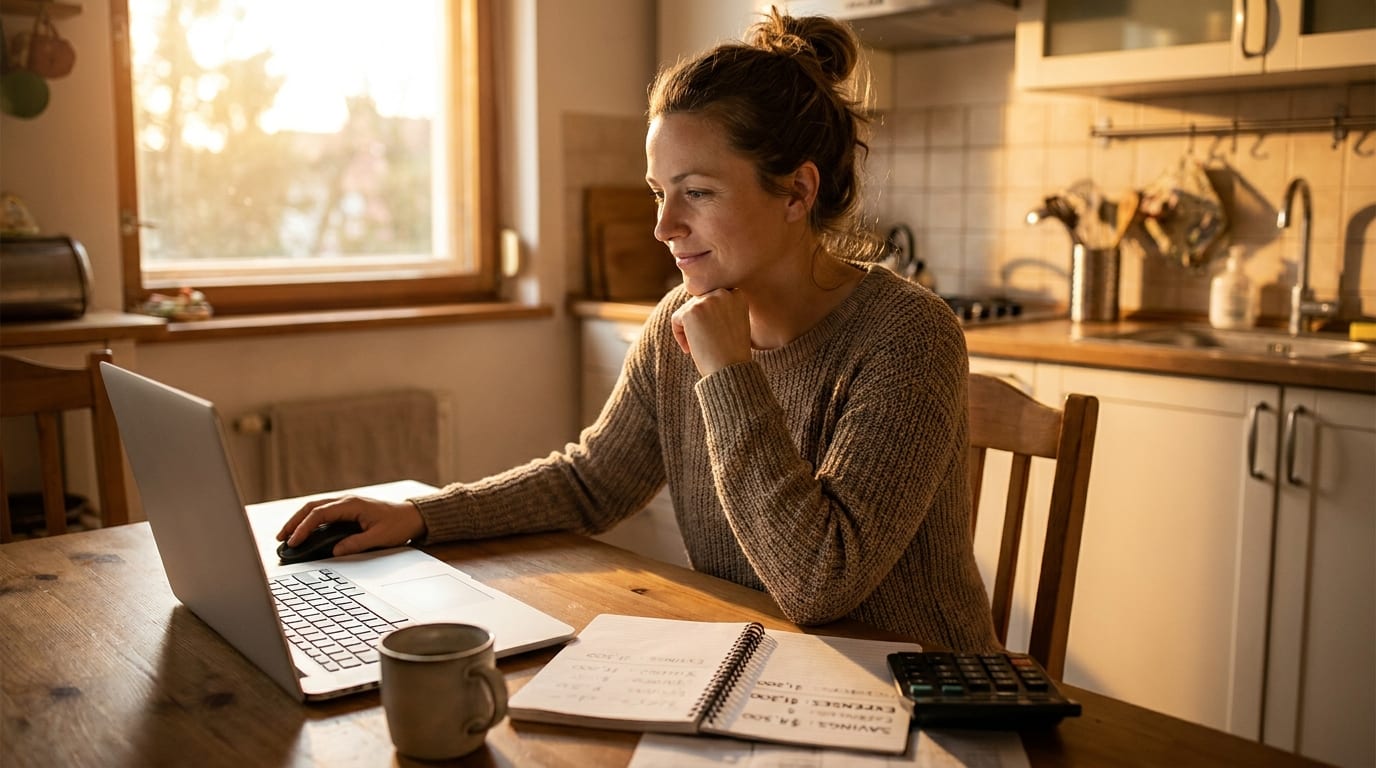
Somewhere after a few months of steady bookings, most lash artists start seriously considering whether it’s time to leave their day job and lash full time. It’s an exciting decision, but also a financial one, and going into it with a real number in mind, rather than just a feeling that things are going well, makes the difference between a confident transition and a stressful scramble a few months in.
Free Guide
Get Your Free Lash Extensions Starter Guide
A $17 value, yours free today. We'll send the guide straight to your inbox in the next minute.
You'll also get occasional lash tips by email. Unsubscribe anytime.
Why “It Feels Like Enough” Isn’t A Real Financial Plan
A single great month of bookings tells you your ceiling, not your reliable income, and only reliable income should factor into quitting a steady paycheck.
It’s easy to look at your best month lashing on the side and assume that’s roughly what full-time income would look like, but a side hustle’s best month is often boosted by a specific event, a wedding season spike, a holiday rush, a referral wave, that doesn’t repeat every single month. Before making the decision, look at your average income across several consecutive months, including your slower ones, since that average is a far more honest picture of what you can actually count on once your day job paycheck disappears.
Building A Real Savings Cushion First
A commonly cited target is three to six months of your full personal living expenses saved specifically as a cushion, kept separate from whatever you’re setting aside to buy supplies or cover business costs. This isn’t money you expect to spend, it’s protection against a slower stretch happening right as you’re adjusting to full-time lash income, which is a genuinely common pattern since new full-time availability doesn’t always translate into an immediately full calendar.
Separating Business Expenses From Personal Living Costs
Before you can calculate a meaningful savings target, get clear on the difference between what your lash business costs to run, supplies, adhesive, workspace rent, continuing education, and what you personally need to live, rent or mortgage, groceries, insurance, and everything else unrelated to the business itself. Read more on monthly supply costs after a lash course to get a realistic sense of the business side specifically, since conflating the two makes it much harder to know what your lash income truly needs to cover.
Testing The Waters With Reduced Hours First
If your current job allows it, dropping to part-time hours before quitting entirely gives you a lower-risk way to test whether more available booking time actually converts into more income, rather than betting everything on an assumption. This middle step reveals real information: does your calendar genuinely fill up when you have more daytime availability, or does demand stay roughly the same regardless of your own schedule? That’s valuable information to have before removing your safety net completely.
Planning For Slower Months Honestly
Even after building a full client base, lash income tends to fluctuate with the seasons, a pattern worth planning for rather than being surprised by after you’ve already quit your job. Read surviving the slow season in your lash business for a fuller look at building a buffer for the predictable quieter stretches every lash business experiences, since that seasonal dip matters even more once lash income is your only income.
Accounting For Taxes As A Newly Full-Time Lash Artist
A steady job typically withholds taxes automatically from every paycheck, something that stops the moment your income shifts entirely to self-employment. Set aside a portion of every payment you receive specifically for taxes, and look into whether quarterly estimated tax payments apply to your situation, rather than discovering a large tax bill you didn’t plan for the following spring. This is a detail that’s easy to overlook in the excitement of finally going full time, but it belongs in your financial planning from the very first full-time month, not as an afterthought once a bill arrives.
Health Insurance And Benefits You’ll Need To Replace
A steady job often comes with benefits that are easy to overlook until they’re gone, health insurance, retirement contributions, paid time off. Price out what replacing these actually costs as an independent lash artist before quitting, since that number belongs in your full financial picture alongside rent and groceries, not as an afterthought you deal with after the transition is already underway.
Accounting For Ramp-Up Time After You Quit
Even with strong part-time income, going full time often means your calendar needs time to actually fill with the extra availability you now have, clients don’t always book faster just because you have more open slots the moment you quit. Budget for a realistic ramp-up period, a few weeks to a couple of months, where your income might temporarily dip below your part-time average while your booking rhythm catches up to your new full-time schedule, rather than assuming the transition happens instantly the day you leave your job.
Talking To Your Household About The Transition
If you share finances with a partner or family, this decision affects more than just your own comfort with risk, and having a direct, numbers-based conversation before quitting avoids a lot of tension later. Walk through your savings cushion, your average income calculation, and your ramp-up expectations together, so everyone understands the plan isn’t a leap of faith, it’s a calculated decision with a clear cushion built in if the first few months run leaner than hoped.
Giving Yourself A Real Decision Point, Not Just A Deadline
Rather than picking an arbitrary date to quit, set a specific income and savings threshold you’re aiming to hit first, a target average monthly income sustained for a set number of months, alongside your savings cushion. That gives you an objective signal to act on instead of a countdown clock that pressures you to quit before the numbers are actually ready, or holds you back with fear long after they are.
Revisiting The Decision If Something Changes
Committing to a savings target and an income threshold doesn’t mean the decision has to be permanent or all-or-nothing once you’ve made it. If your circumstances shift, a slower month than expected right after quitting, an unexpected expense, an opportunity to pick up occasional part-time work again temporarily, it’s reasonable to adjust the plan rather than treating any change of course as a failure. The goal of planning with real numbers in the first place is precisely so you have a clear basis for recognizing when something needs to change, instead of only feeling vaguely like things aren’t going as hoped.
What Our Course Includes
The Lash Extensions Master Course gives you the technical foundation to build the client base this decision depends on, for a one-time $97 payment with lifetime access.
Final Thoughts
Quitting your day job for lash extensions full time is a decision worth making with real numbers, not just momentum from a good month. Build your savings cushion, calculate your honest average income, and consider testing reduced hours before cutting your paycheck completely. For more on building toward this point, see running a lash business as a side hustle while working or how much you can earn after lash extension training.
Free Guide
Get Your Free Lash Extensions Starter Guide
A $17 value, yours free today. We'll send the guide straight to your inbox in the next minute.
You'll also get occasional lash tips by email. Unsubscribe anytime.
Frequently Asked Questions
A common guideline is three to six months of your full personal living expenses saved, separate from your business supply budget, giving you a real cushion if bookings dip while you're transitioning away from steady employment income.
Keep Reading
Popular Lash Training Guides
- Minimum Age For Eyelash Extension Training
- Eyelash Extension Training Cost In 2026: Real Breakdown
- Lash Tech License Requirements By State
- Is It Hard To Learn Eyelash Extensions? Honest Answer
Ready to go from reading to doing? See the full Lash Extensions Master Course or browse all lash training guides.